
Getting the job done means trusting workers to spend company money—and keeping track of where it goes. In industries like plumbing and construction, employees often carry company cards to buy fuel and supplies, while office staff sort through receipts to check that spending stays within bounds. Coast, a New York-based startup, wants to make this process more transparent by pairing company payment cards with software that helps businesses control spending and track purchases made on the job.
On Thursday, the company, founded in 2020 by former Wall Street engineer Daniel Simon, announced a $35 million growth equity round that closed in October. It plans to use the funding to build out a platform that helps businesses manage employee spending, facilitate payments to vendors, and automate accounting tasks.
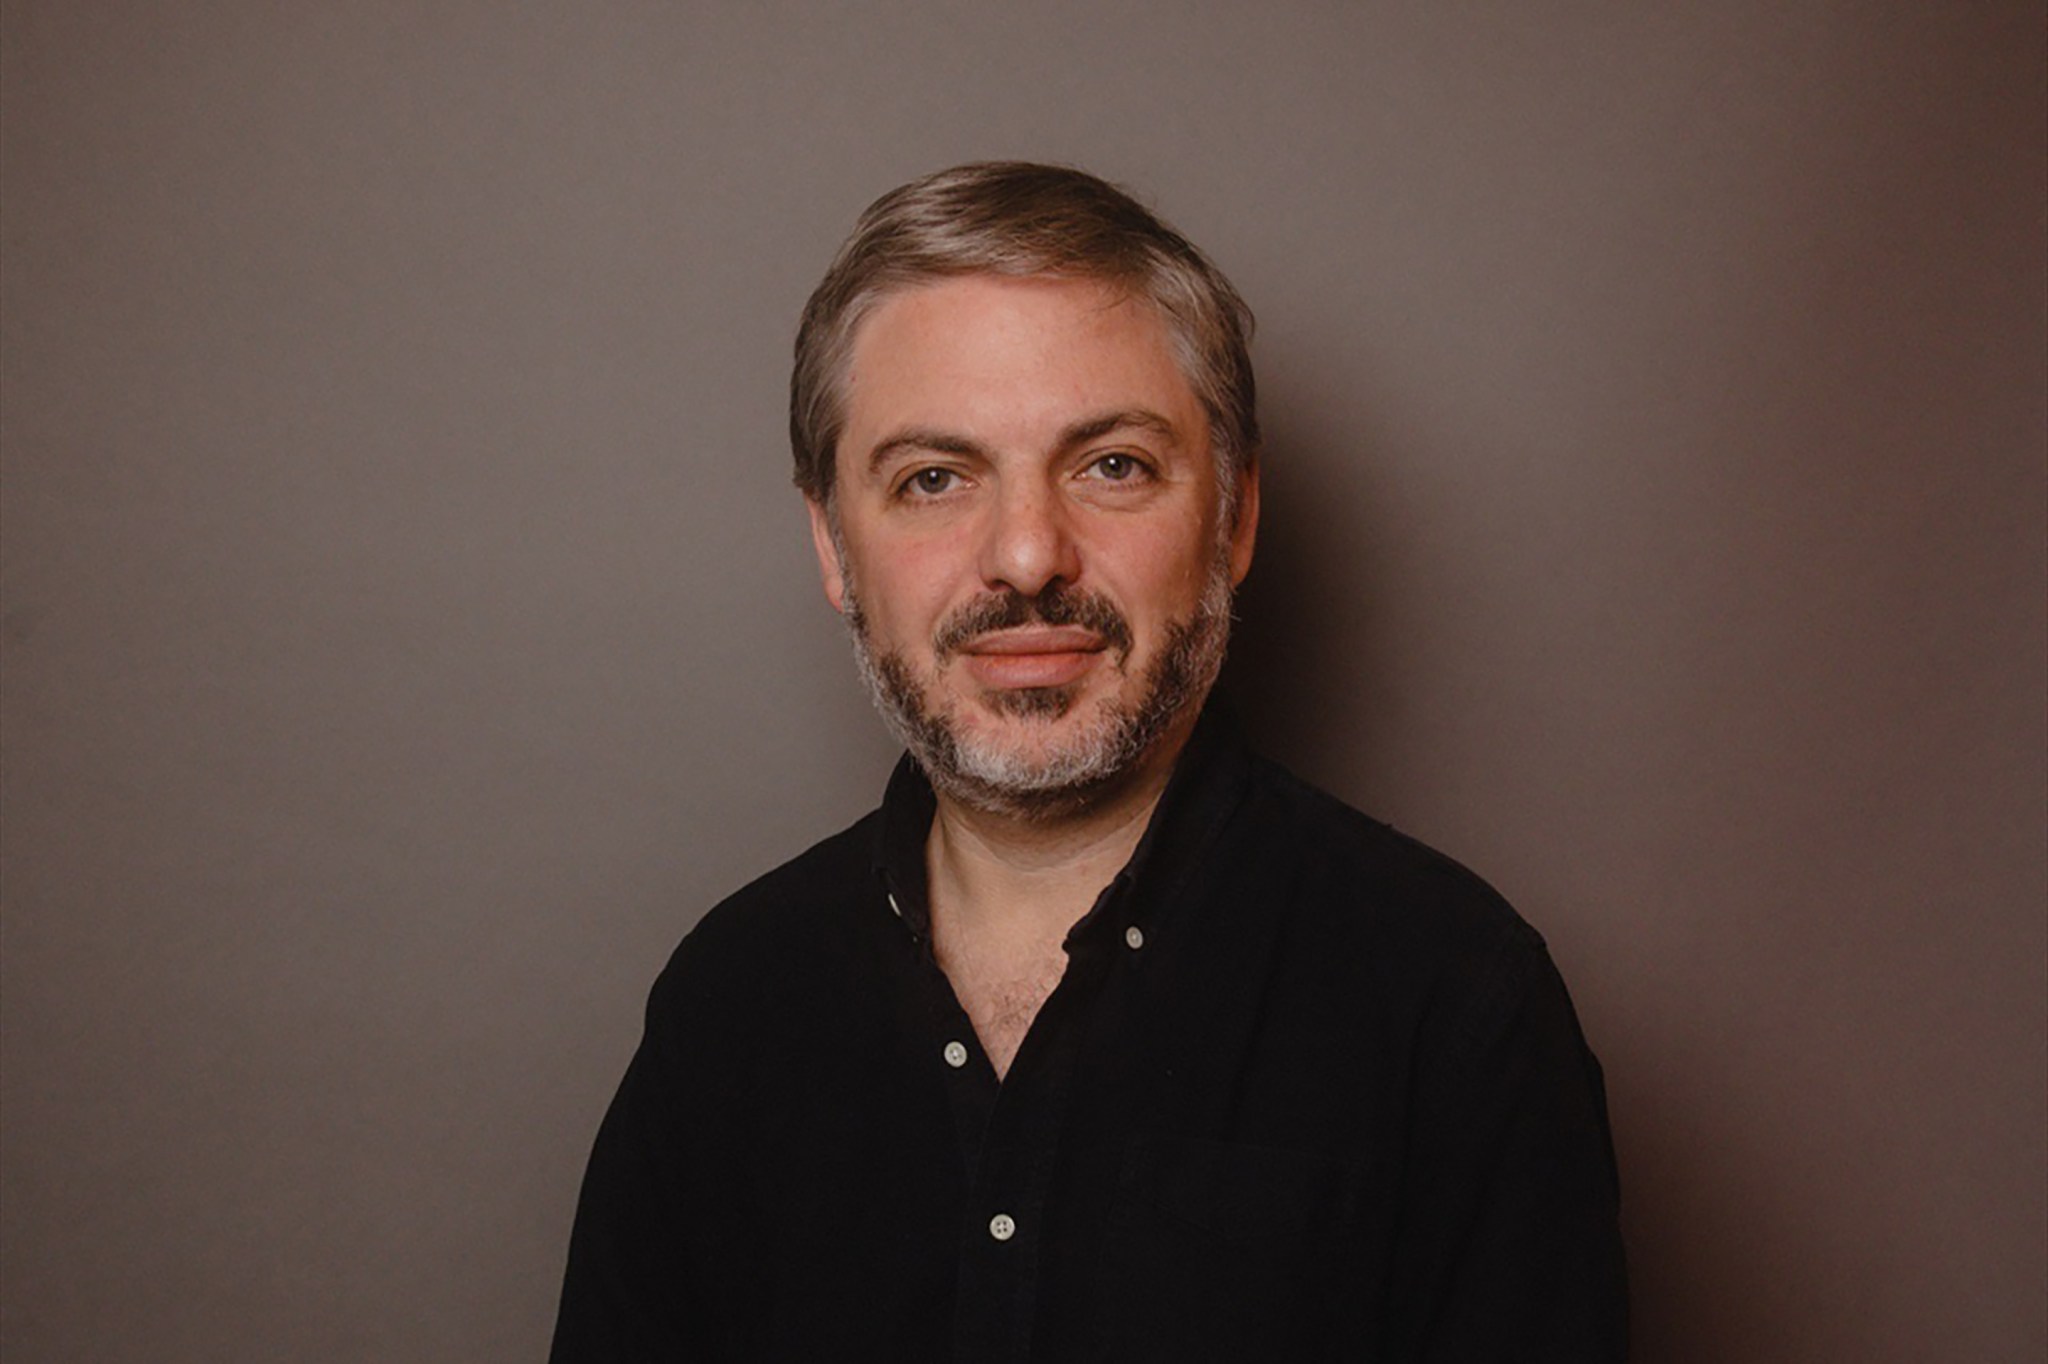
“If you run a plumbing business or an HVAC… and you need to give the technician who works for you the company credit card when they take the van out to go to their job… you need really specialized control, security, visibility, [and] reporting,” Simon, who serves as Coast’s CEO, told Fortune.
It works like this: A worker picks up a company card and checks in by text or app. That links the card to their identity and the spending limits their employer has set. Coast can then use vehicle location data to check whether the company van is at the gas station where the card is used—and block the purchase if it isn’t. Once a purchase goes through, the software sends the transaction details to the company’s accounting system, so office staff have fewer records to enter and match by hand.
Thomvest Ventures led the growth equity round, joined by new investors Intuit and Small World Capital. Returning backers included ICONIQ Growth, Accel, Insight Partners, Better Tomorrow Ventures, Avid Ventures, Vintage Investment Partners, Synchrony, RXR, and The Fintech Fund. The funding follows Coast’s Series B, which raised $40 million, and an earlier $92 million funding round. Coast declined to disclose its latest valuation.
The workers behind the AI boom
Though artificial intelligence promises to automate office work, its growth depends on workers who build data centers and upgrade power grids. U.S. demand for skilled trades is growing three times faster than for desk jobs, with openings for heating, ventilation, and air conditioning technicians up 78% and broader trade postings up 30%, according to a March report by staffing company Randstad USA. Its research also found that 102 workers leave the trades for every 100 who enter, putting pressure on businesses to do more with fewer people. Coast sees an opportunity to sell payment tools to these businesses in a market it estimates at $120 billion.
“You are taking time that might have otherwise been spent [on] back office work and giving that back to the people in the trades to work on what they are really focused on,” Don Butler, managing director at Thomvest Ventures, told Fortune.
Simon first saw an opportunity to tap into this market during the height of the pandemic, shortly after he sold his previous payments startup, Bread, for $500 million in 2020. The sale marked the latest milestone in a career that began on Wall Street, where Simon built trading software for investment banks and hedge funds before earning law and business degrees from Yale University.
But while banks and tech companies used modern software, he saw plumbers, electricians, and heating and cooling technicians rely on payment tools designed before smartphones existed.
Today, Coast has about 135 employees across its New York headquarters and a Utah office, and serves thousands of businesses, including Tristate Plumbing, Texas Solar Outfitters, and Verde Property Services. The company is not yet profitable and says it prioritizes growth, with revenue reinvested in its products and efforts to attract customers.
This story was originally featured on Fortune.com