
Wall Street analysts are anticipating something of a standoff between the Federal Reserve and the White House this week, with expectations that the Federal Open Market Committee (FOMC) meeting (concluding Wednesday) will result in a hike in the base rate.
This would be precisely the opposite of what President Trump wants to see in monetary policy. The White House has lobbied (to an extreme degree) for a loosening of financial conditions.
But everyone from the White House to Wall Street to the central bank will be closely watching the flexing of the bond market’s macroeconomic muscle—and even President Trump has been warned against testing its patience.
The September FOMC meeting comes at a time when the Fed’s dual mandate of maximum employment and price stability may warrant action. The latest jobs report came in stronger than expected, while inflation remains stubbornly above the central bank’s 2% target.
And while the Fed could be implored to “look through” inflation because it is driven by a supply-side shock in oil prices, doing so could call into question its credibility if it is seen as shying away from action.
Indeed, following the conclusion of the June FOMC meeting this year, the bond market’s reaction was clear: Longer-dated yields pushed higher, as investors absorbed a hawkish narrative from the Fed, but without the monetary policy follow-through. The central bank’s base rate and bond yields generally move together over time; if bond yields spike while interest rates stay flat, it suggests investors perceive risks in the economy that policymakers are not yet addressing, be it inflation expectations or economic instability.
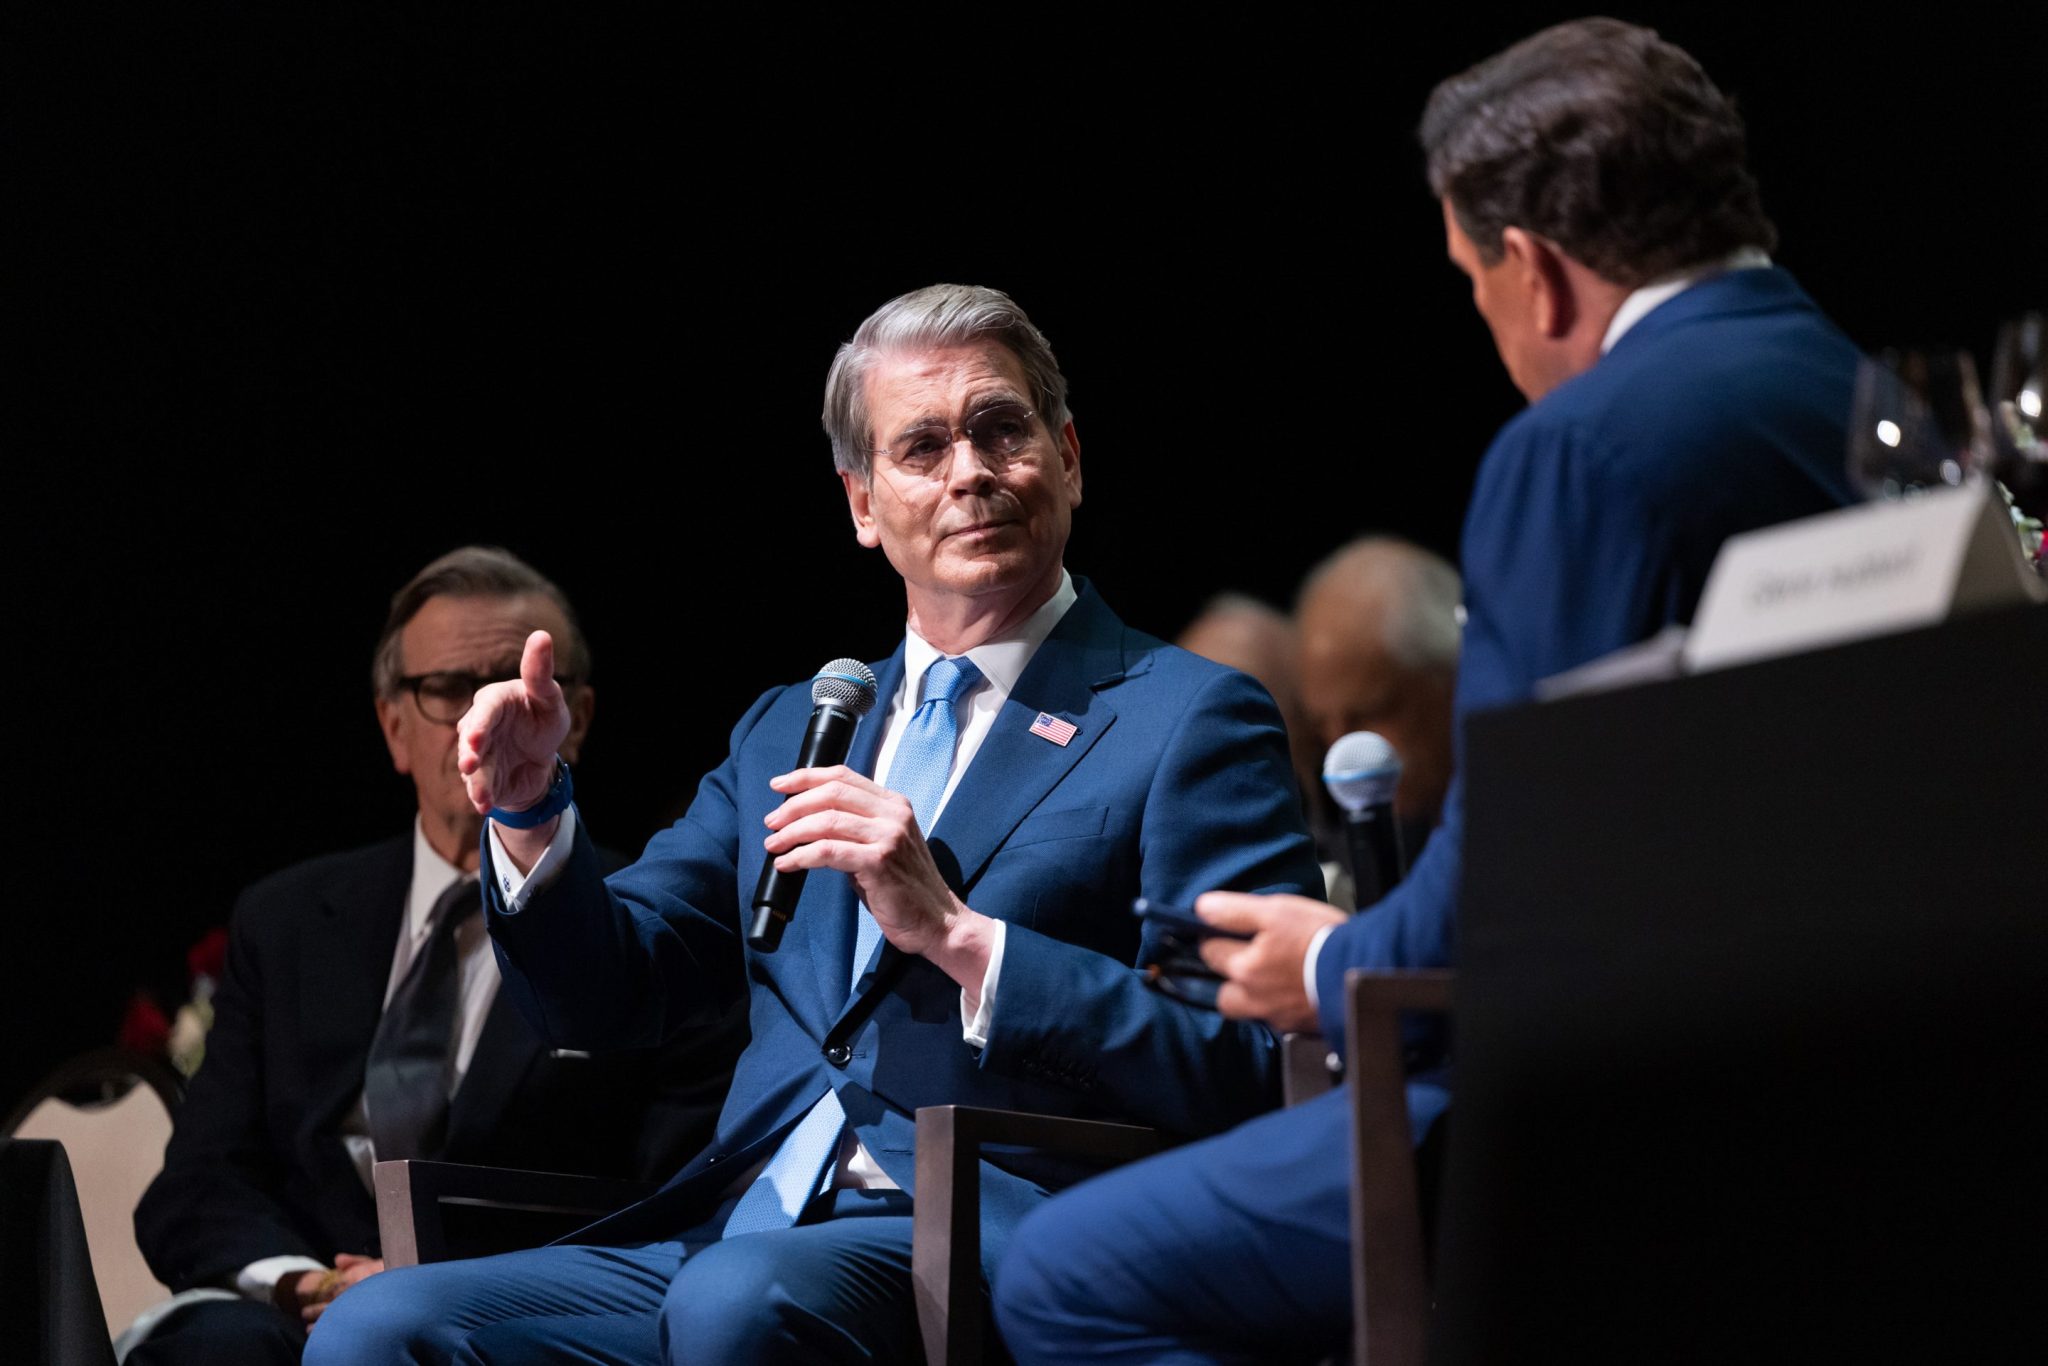
Treasury Secretary Scott Bessent has previously signaled that the White House is cautious about pushing too hard in defiance of the bond market—even if a hold or a hike in the base rate is politically unpalatable. Speaking at the Economic Club of New York in June, the Treasury Secretary was asked whether Chairman Warsh was facing increasing pressure from the executive branch to cut, even though the data suggest the opposite.
Bessent responded: “I am confident that the Fed chair will … optimize the path for both inflation and economic growth. The president said at Chair Warsh’s swearing-in [ceremony] that he would be independent, that he should do what he wants.”
“Look, the president understands—he and I have talked about it quite a bit—… the bond market has taken out more governments than howitzers. So I believe that he has complete confidence in the Fed chair to do the right thing.”
While it is not the Fed’s job to heed or support the bond market, Bessent’s acknowledgment of its power gives the FOMC room to operate. Indeed, Bessent recently launched a multi-billion-dollar Treasury buyback scheme that briefly pushed yields lower to ensure greater market liquidity.
And while the Fed’s independence is legally mandated and should not be dictated by either politicians or investors, the experience of former Fed chairman Jerome Powell’s final year in the top job shows how exposed the central bank can be when the White House wants a different path for interest rates. For Warsh, early in his tenure, the bond market might provide an important reminder to the administration about being seen to push the Fed too far.
Wall Street takes
Wall Street doesn’t want to see a further uncoupling between the heavy hand of the bond market and the central bank of the world’s largest economy.
As Ryan Sweet, chief global economist at Oxford Economics, noted Friday, “the bond market could be losing patience with central banks sitting on the sidelines, forcing them to act.” He explained: “If a central bank remains on the sidelines while inflation is running hot or energy/supply shocks are pushing prices higher, the bond market could interpret this as policymakers accepting a higher path for inflation rather than acting to fight it, leading to higher long-term interest rates.”
UBS’s Paul Donovan had a similar take for his clients in an audio note this morning, saying that “if Warsh surprises financial markets, it risks reawakening accusations of being a ‘sock puppet’ and raising credibility questions which would require a risk premium in bond pricing. That would raise real borrowing costs for the government and private sector, with implications for investment and trend growth.”
This story was originally featured on Fortune.com